For most people, accumulation is the longest phase of their financial lives. When that phase transitions into drawdown, it is among the most critical changes a client will ever make. Going from building wealth to enjoying it requires an entirely different strategy. At the heart of that strategy is cash. Yet, too often, this asset is misunderstood and dismissed dead capital.
For financial advisers, redefining the role of cash for those about to cross the threshold into retirement is essential. Holding two to three years of precautionary cash is the cornerstone of a resilient retirement plan, rather than a hallmark of one overly cautious one.
During working years, surplus savings are naturally shifted into longer term investments, equities and pension funds. Time is largely on the client’s side. Once retirement begins, the objective of those savings becomes income generation rather than just capital growth.
Clients are no longer feeding portfolios, but drawing from them, which can introduce a vulnerability known an as the “sequence of risk”. If a client is forced to liquidate equities during a market downturn to fund living expenses, they might lock in permanent losses. It is in these situations where structured cash management can be powerful hedge.
Asset managers and insurers offering professional retirement products always incorporate a dedicated cash allocation – usually built with a three-year buffer to cover living expenses.
But why is that considered to be enough, when life expectancy continues to grow, with inflation and other economic pressures continuing to push the cost of living upwards?
The length of this buffer helps prevent forced selling or knee-jerk reactions during a market correction. If there’s a sudden drop, clients can draw from their cash savings, while their equity holdings have time to recover. There is also significant psychological safety in knowing that immediate living costs are covered for at least of couple years. This removes anxiety around short-term volatility, while also providing some peace of mind during moments of market instability.
Holding cash does not mean retirees miss out on market gains. Instead, cash is better seen as an insurance policy to protect other growing assets from being sold at the worst possible time. This where advisers can really help their clients get the most out of their cash holdings. By directing clients away from jumping in and out of cash and trying to time the market, advisers can empower retirees to be more strategic with their savings.
This is done by bucketing cash into two general pots. The first is the short-term cash which is held defensively and is used as the highly liquid income buffer to support immediate needs without touching growth assets. The second bucket holds those longer-term investments, which should include a mixed asset portfolio across equities or fixed income instruments tailored to the client's horizon and legacy goals.
Given the competitive rates available today across both easy access and fixed-term accounts, cash does not need to be an idle asset any longer. Deployed strategically, cash can yield attractive returns, and help grow a portfolio rather than drag it down.
Retirement planning is ultimately about providing peace of mind. By guiding clients through the shift from accumulation to drawdown, and anchoring their strategy with a robust cash buffer, advisers can turn uncertainty and anxiety into lasting financial confidence.
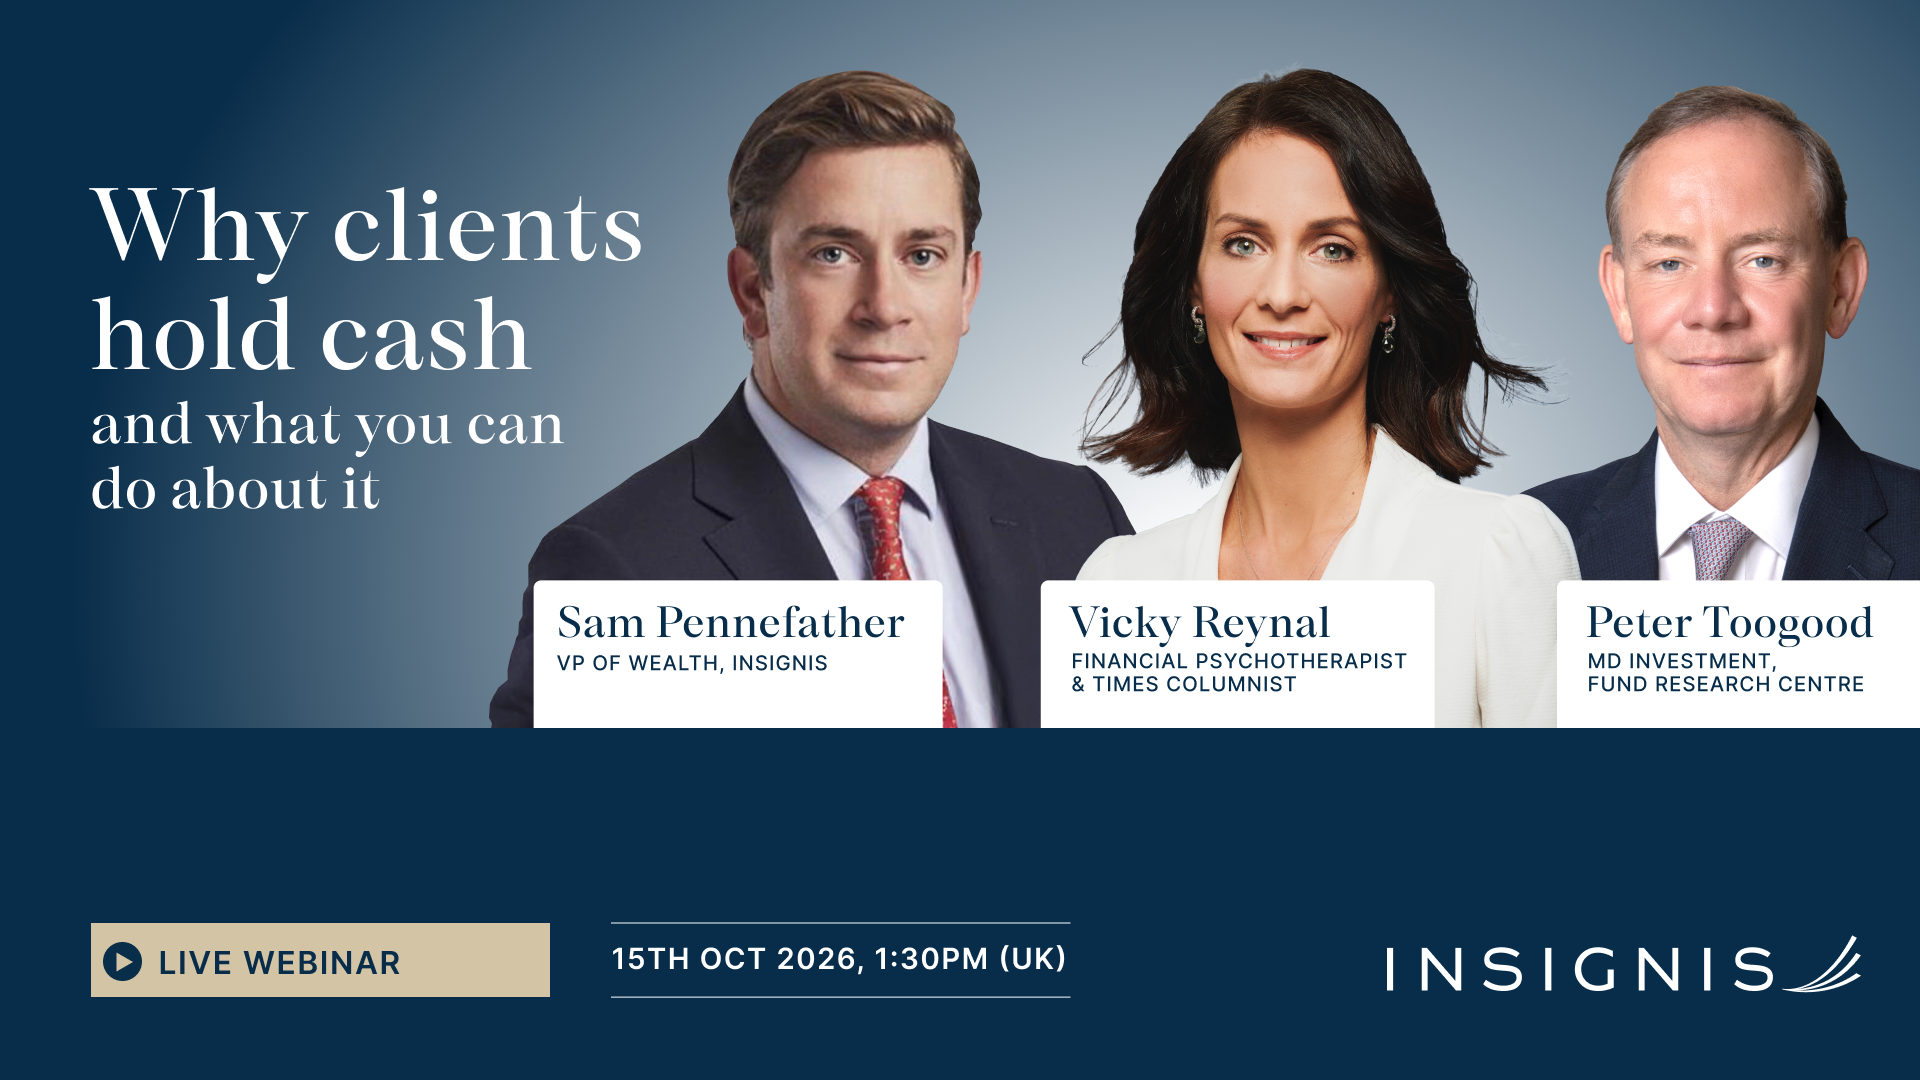
Want to explore how cash can anchor your clients’ retirement strategy? Join Vicky Reynal, financial psychotherapist, and Peter Toogood of the Fund Research Centre in our latest webinar.
8 Devonshire Square, London EC2M 4YJ
St John’s Innovation Centre, Cowley Rd, Milton, Cambridge CB4 0WS
+44 (0)1223 200 674